Laval Auditor General’s Annual Report Identifies Gaps in City Planning and Management
Credit Ville de Laval
The City of Laval’s Auditor General, France Lessard, tabled her 2025 annual report at city council in August, identifying several areas where improvements could be made. The report examines a number of performance audits, including library planning, the governance and management of municipal asset maintenance programs, the awarding and administration of contracts for digital projects, and the implementation of recommendations from previous audits.
According to Ms. Lessard, audits conducted in 2025 and previous years have identified recurring challenges, particularly regarding the quality of asset data, updates to strategic and master plans, as well as accountability and governance.
A question of planning and accountability
The Auditor General found that several of Laval’s planning documents are not always aligned with one another and that the City does not consistently use performance indicators to assess whether its objectives are being met.
This issue is particularly relevant when it comes to major investments. Without sufficiently detailed financial projections, reliable data or clear accountability mechanisms, it can be more difficult for the City to determine whether its investments are addressing identified needs.
According to Ms. Lessard, these concerns were reflected in several of the audits examined in the report.
Millions of dollars in investments under review
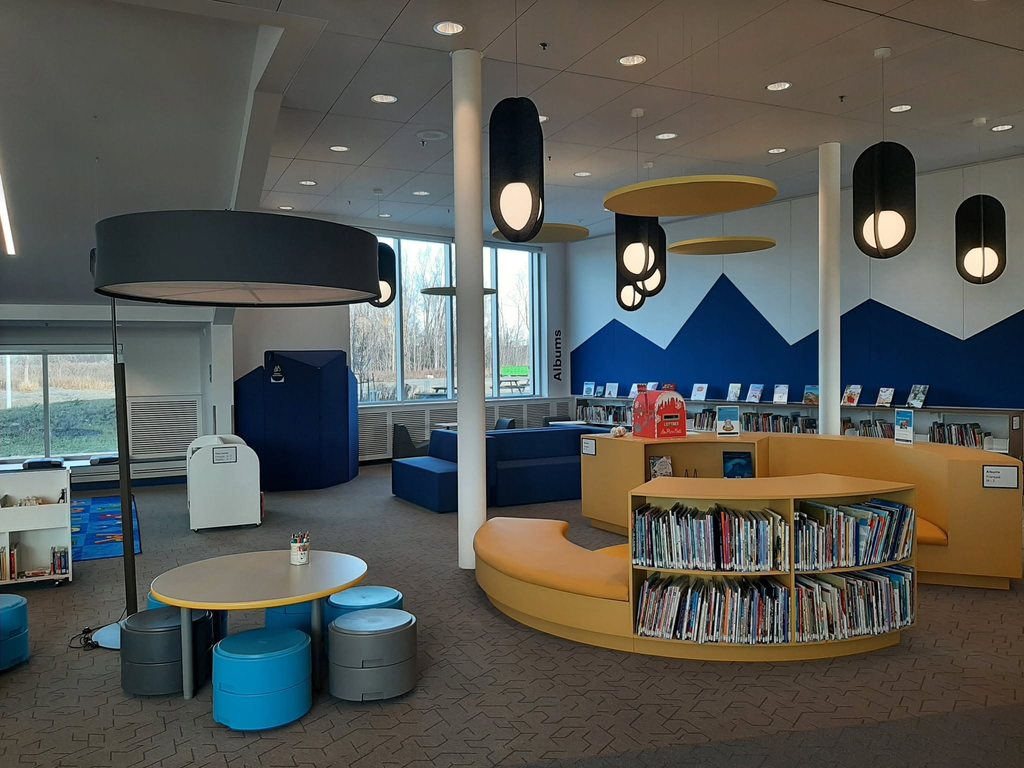
Laval is planning significant investments in its library network. The City currently has nine libraries and plans to add two more between 2026 and 2028, with a long-term objective of 17 libraries by 2036.
The projects represent approximately $108.2 million in planned investments. However, Ms. Lessard’s audit found that Laval’s planning process does not yet provide sufficiently detailed planning for the financial and human resources that will be required to operate the expanded network.
Some projects that had previously been identified as priorities have also yet to be completed. The report points to limited monitoring and the absence of a formal accountability process.
The findings raise questions about whether the planning surrounding these investments is sufficiently comprehensive.
Keeping track of Laval’s existing infrastructure
While the City prepares to expand some of its public infrastructure, the Auditor General also examined how Laval manages the assets it already owns.
A total of $52.2 million has been allocated to asset maintenance programs. According to the audit, however, the City does not always have complete and up-to-date information about the condition of its infrastructure.
Some assessments of municipal assets are incomplete or outdated, making it more difficult to determine which maintenance projects should be prioritized. According to the report, the tools currently being used also do not allow the City to accurately assess its asset maintenance deficit or measure the impact of investments made to reduce it.
Ms. Lessard also identified weaknesses in the planning of maintenance projects, including insufficiently defined costs, scopes and timelines. Governance and accountability mechanisms intended to guide asset management have also not been fully implemented.
Digital contracts reveal another area for improvement
Lessard’s office reviewed four contracts involving the acquisition of information technology solutions, representing a combined value of $11 million. It also examined 24 professional services contracts worth $95 million.
Although the City generally obtained the resources required for its projects in accordance with applicable rules, the audit identified areas where contract planning and management could be improved.
Among the concerns raised were limitations in needs assessment, market analysis and the monitoring of suppliers’ work. In some cases, suppliers continued to provide services after authorized amounts had been reached or after their mandates had expired, without a formal renewal being completed.
The report also found that oversight of external consultants varied and was not always structured. For fixed-price contracts, documentation confirming the quality and approval of deliverables was not always completed before payment.
Recommendations are being gradually implemented
The report also provides an overview of Laval’s implementation of recommendations issued in previous years.
For the 2021 annual report, 89% of recommendations had been implemented by the fourth year of follow-up, compared with 98% for the 2020 report.
More recent recommendations remain at earlier stages of implementation. During the first follow-up of the 18 recommendations included in the 2023 annual report, 6% had been implemented. Meanwhile, 35% of the 31 recommendations from the 2022 annual report had been implemented by the time of their second follow-up.
Four action plans associated with 58 recommendations under review have also been completed.
Continued oversight ahead
Despite the shortcomings identified in the report, the Auditor General said Laval’s administration is progressing in implementing previous recommendations.
“The administration is on the right track to implement the majority of the recommendations,” Ms. Lessard said. “However, it will need to maintain its efforts to complete the necessary actions and achieve the expected results.”
Ms. Lessard also indicated that her office will continue monitoring recommendations related to the City’s long-term investment planning and its three-year capital investment program for at least another two years.